What the market priced
On Thu 5 Nov 2026, Wall Street treated the Democratic sweep, and especially Gina Hinojosa's win in Texas, as a hard brake on the AI data-center boom.
Official US cash closes:
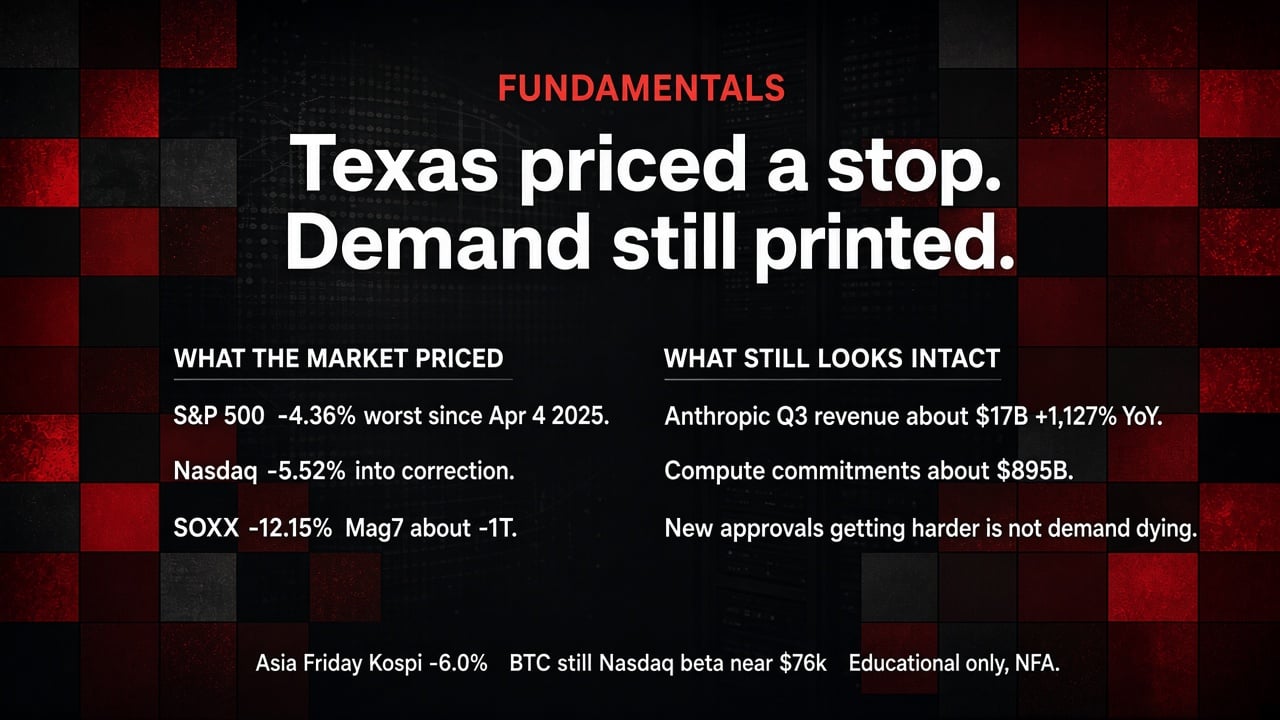
- S&P 500 7,353.73 (−4.36%)
- Nasdaq Composite 24,315 (−5.52%, into correction)
- Dow 51,523.06 (−3.44%, about 1,833 points)
- Semiconductor ETF SOXX 131.90 (−12.15%)
- Philadelphia Semiconductor Index (SOX) about −12.3% (NBC), worst day since March 2020
CNBC put the Magnificent 7 aggregate loss above $1T. Nvidia alone lost more than $440B of market value and closed at $181.60 (−9.26%).
NBC framed about $2.3T erased from the Nasdaq 100 and about $2.8T from the S&P over the full session. That is session scale, not a stopwatch claim.
Calibration: for the S&P, Nasdaq, and Dow, this was the worst day since the Apr 4, 2025 tariff shock often nicknamed Liberation Day. It was not "the worst session in Wall Street history."
What still looks intact
An amended Anthropic S-1 (filed Nov 2) is the cleanest public demand signal we have right now.
From the SEC filing and CNBC write-up:
- Q3 revenue about $17.0B, up 1,127% year over year
- Nine-month revenue $33.24B
- Purchase and lease commitments about $895.4B, almost all compute and infrastructure
Simple math: $17B in one quarter annualizes near $68B. That is not the same as Anthropic's own Run-Rate Revenue metric, and the filing we opened did not publish a verified October ARR print. Do not invent one.
Read the split carefully:
- New approvals, water rules, power-bill protections, subsidy cuts, union labor, and local veto rights are the political pressure points (Texas Tribune, Data Center Dynamics, Reuters).
- A pause on NEW greenfield approvals is not the same thing as AI demand disappearing.
- Claims that already-permitted projects still cover 2027 into early 2028 are industry interpretation, not a verified overnight decree. Treat that as a watch item, not a fact.
What actually printed in the chip complex
Memory and optics took the harder hits. GPUs were ugly, but not alone:
- SanDisk (SNDK) −22.3%
- Astera Labs (ALAB) −19.6%
- Lumentum (LITE) −18.7%
- Micron (MU) −17.5%
- AMD −17.3% to $404.40
- Arm −13.1%
- Broadcom (AVGO) −10.4%
- TSMC ADR (TSM) about −11%
- Nvidia (NVDA) −9.3%
Software and consumer mega-caps fell less than the chip complex (Apple, Microsoft, Alphabet, Meta, Amazon in the low single digits to mid single digits on the heatmap). Tesla was closer to the AI beta names at about −11%.
Asia Friday
Seoul did not fade the story. It amplified it.
Friday Kospi closed at 5,059.69 (−6.02%). The index had already been near 5,384 the prior session. Early Friday it plunged more than 8%, triggering a circuit breaker, then a sell-sidecar (a program-trading brake). Foreigners were net sellers of about 2.77 trillion won. Samsung Electronics −6.4%. SK hynix −10.4%.
Korean desks themselves called a full US buildout halt unlikely. The priced risk is delays and higher costs, not zero AI demand.
Cloudflare after the close
Cloudflare (NET) reported after the Thursday cash close:
- Q3 revenue $782.5M (Street was roughly $737 to 739M)
- Q4 guide $845 to 846M (Street near $798M)
- Full-year 2026 guide about $2.963B
- Non-GAAP gross margin 72.4% (the soft spot)
- After-hours bounce about +14.5%
One print does not fix a tape. It does say edge and cloud demand did not vanish overnight.
Crypto beat
Bitcoin did not act like a haven. It acted like Nasdaq beta.
- Thu 5 Nov UTC close: BTC near $75,970 (−5.7%), ETH near $2,235 (−7.7%)
- Liquidations over 24 hours: more than $1B, mostly longs
- Fri 6 Nov (CoinDesk, 6:49 a.m. EST): BTC steadied near $76,150 after a bounce from about $75,200
Into Friday afternoon Asia/Tbilisi time, crypto was still hugging the risk tape. No clean decoupling yet.
What I'm watching
- Texas comments on what "moratorium" covers: new approvals only, or projects already in flight.
- Contagion talk in other data-center states (Georgia, Ohio, and peers).
- Tech CEO language on power, permitting, and CapEx timing.
- Anything that clarifies Anthropic's IPO path and compute commitments.
- Whether Friday's US cash session (opens 18:30 Asia/Tbilisi) accepts Thursday's wipe or tries to buy the political overreaction. Premarket earlier showed chip names bouncing. That is not a close.
My view
Thursday paid a political-friction premium as if the AI buildout had stopped. The Anthropic filing still says lab demand is enormous. The honest split is: new data-center approvals get harder and slower; that is not identical to demand dying.
For crypto readers: until BTC stops tracking Nasdaq on these tapes, treat it as high-beta risk, not digital gold.
Educational only. High risk. NFA.
Want the next Fundamental Desk note before it hits the timeline? Telegram VIP access is on this website.
Sources:
- Frenchie starting-point recap
- Texas Tribune: Hinojosa and data-center pause
- Reuters via Investing: Texas data centers after Hinojosa
- Data Center Dynamics: Texans First priorities
- Anthropic S-1/A (SEC)
- CNBC: Anthropic amended S-1
- CNBC: Mag7 ~$1T, session stats
- NBC: tech plunge, SOX −12.3%, session wipe
- Yahoo Finance: SOXX history
- Yahoo Finance: NVDA history
- Yahoo Finance: AMD history
- Yonhap: Kospi Friday
- Seoul Economic Daily: foreign selling / sidecar
- Cloudflare IR: Q3 2026
- CoinDesk: BTC steadies near $76k